Your renewal increase isn't inevitable.
|
Three assumptions worth challenging before accepting your next benefits renewal.
|
|
|
|
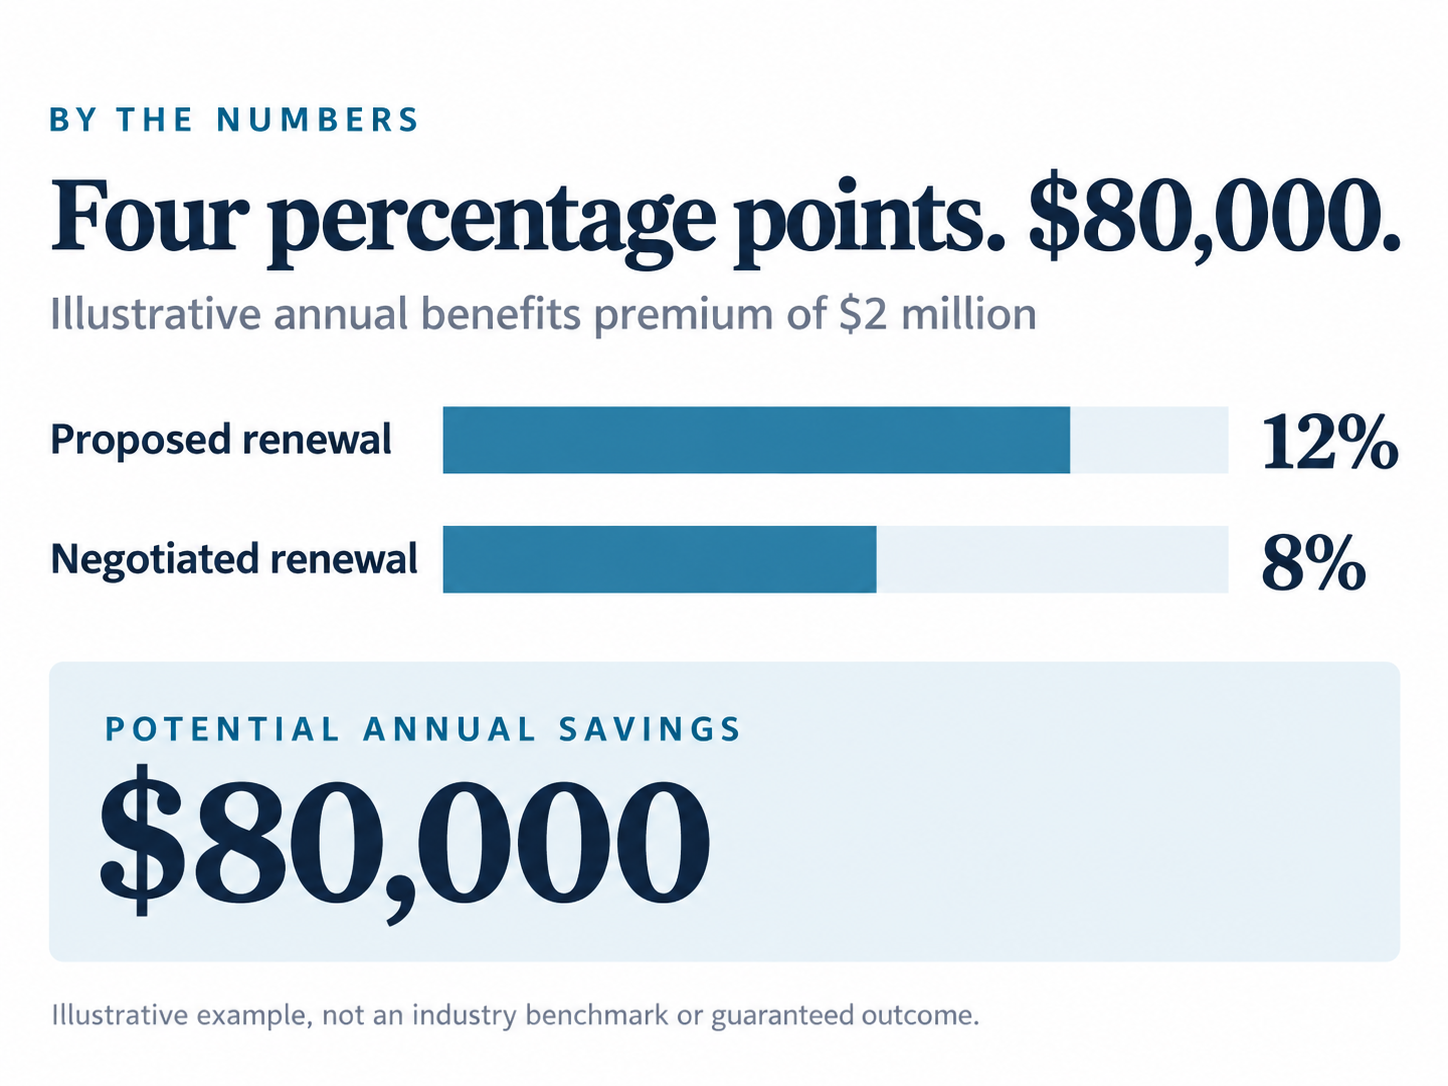
Your insurer just delivered a 12% renewal increase. It might be justified. It might not.
|
|
But here's the question: Are you negotiating the number, or challenging the assumptions that created it?
|
|
|
| Here's the thing... |
| Your renewal isn't one number. It's a collection of assumptions about future claims, inflation, administration, pooling and insurer margins. |
| Before accepting an increase, challenge three things: |
| 01 / Claims credibility. Is the insurer placing appropriate weight on your own claims experience? |
| 02 / Trend assumptions. Are projected drug, dental and health inflation factors supported by credible data? |
| 03 / Pricing margins. Are administration fees, pooling charges and profit provisions still competitive? |
|
|
Don't negotiate the percentage. Challenge the assumptions that created it.
|
|
Ask your advisor which three assumptions contributed most to your renewal increase and which were independently challenged.
|
|
|
|
|
ONE QUESTION WORTH ASKING THIS WEEK
|
|
"Can our advisor show us exactly which assumptions account for our renewal increase—and which ones have been challenged?"
|
|
|
|
|
Learn how to evaluate renewal assumptions, identify negotiation opportunities and build a stronger renewal strategy.
|
|
|
|
One useful benefits idea. Every week.
|
|
Enjoyed this issue? Forward it to a colleague who makes benefits decisions.
|
|
|
